Do Your Credit Card Rewards Actually Save You Money?
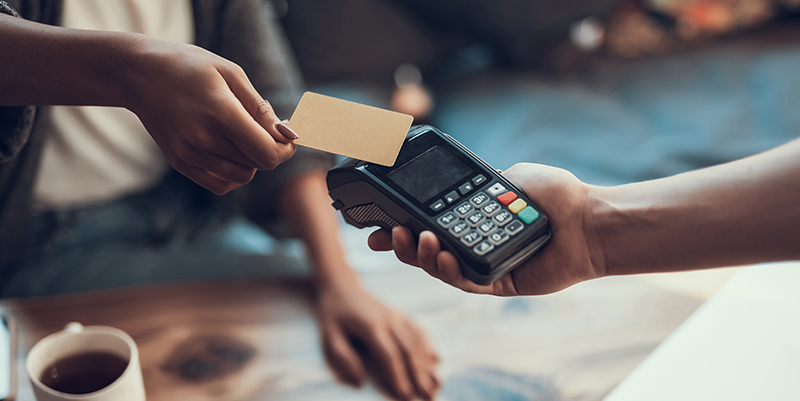
Cash back, travel points, introductory bonuses, and merchant offers can make a credit card feel like it is paying you to spend. Used carefully, rewards can provide real value on purchases you were already planning to make.
But earning rewards is not the same as saving money. The value of those points or dollars depends on what it costs you to earn them.
Start With the Math
A card offering 2% cash back sounds straightforward: Spend $1,000, and you earn $20.
If that $1,000 balance carries over and begins accruing interest, however, the finance charges can quickly exceed the reward. The same applies to cards with annual fees. A $95 annual fee might make sense if the benefits you actually use are worth substantially more, but it becomes another expense if you are not getting enough value from the card.
When evaluating a rewards card, consider the whole picture: the rewards you earn, interest you pay, annual fees, and any other costs associated with the account.
Watch the Spending Requirements
Some cards offer large introductory bonuses after you spend a certain amount within the first few months. Those offers can be valuable when the required spending fits naturally into your existing budget.
The trouble starts when earning the bonus becomes a reason to buy more than you otherwise would.
Before pursuing a welcome offer, ask yourself whether you would make those purchases without the reward. Spending an extra $500 to earn a $200 bonus still leaves you $300 behind if that spending was not necessary.
The same principle applies to everyday rewards. A higher cash-back rate at a particular store does not make an unplanned purchase a bargain.
Know What Your Rewards Are Worth
Not all points are created equal. Cash-back rewards generally have an easy-to-understand value, while points and miles may be worth different amounts depending on how they are redeemed.
Pay attention to expiration dates, redemption minimums, eligible purchases, and whether certain options provide less value than others. Merchant-specific rewards may also encourage you to spend money with a retailer simply because you have points available.
Before choosing a card primarily for its rewards, consider whether those benefits match the way you already spend.
Let Rewards Follow Your Budget
The simplest approach is to treat rewards as a benefit of purchases you were going to make anyway—not as a reason to spend.
If you regularly buy groceries, gas, or other essentials, earning rewards on those expenses may provide additional value. Paying your balance in full when possible can also help prevent interest charges from consuming the rewards you earned.
A good rewards program should complement your financial habits, not change them for the worse.
Before chasing the next bonus or cash-back offer, look beyond the points. The best reward is one that leaves you financially better off after all the costs are considered.
Want to take a closer look at your credit health? Explore Credit Mountain, a Cornerstone Foundation preferred financial wellness provider with tools designed to help users build personalized credit-improvement plans.